Photo by: www.kaboompics.com via Pexels
TL;DR: The first step of the accounting cycle is identifying and analyzing financial transactions using primary source documents. Before any entry reaches a journal or general ledger, accounting teams must verify whether an economic event occurred, measure its monetary value, and confirm it impacts the organization’s financial position. In total, there are eight standard steps in the accounting cycle, serving as the foundation for audit-ready financial statements.
Every accounting system relies on accurate input at the absolute start of the workflow. The first step of the accounting cycle ensures that only legitimate, measurable economic events enter the company’s financial records. Without rigorous transaction identification, unverified expenses, missing receipts, or misclassified invoices can cascade through every subsequent stage, undermining the integrity of your balance sheet and income statement.
- What Is the First Step of the Accounting Cycle?
- Common Source Documents Used in Transaction Identification
- Real-World Examples of Identifying vs. Filtering Transactions
- How Many Steps Are in the Full Accounting Cycle?
- Automation and AI at Step One: Moving from Manual Logs to Optical Ingestion
- Frequently Asked Questions
What Is the First Step of the Accounting Cycle?
The first step of the accounting cycle is the process of identifying, collecting, and analyzing business transactions based on verifiable source documents. It requires financial teams to filter daily operational noise and isolate activities that directly alter an organization’s assets, liabilities, or equity structure.
In technical terms, an event qualifies as an accounting transaction only when it meets three criteria under U.S. GAAP and IFRS framework standards:
- Economic Exchange: Money, goods, services, or legal obligations have been transferred between two or more entities.
- Measurability: The monetary value of the event can be objectively determined in a specific currency.
- Relevance to the Reporting Entity: The financial impact directly belongs to the organization maintaining the ledger.
Understanding where these activities land is vital for legal compliance and structural clarity. As detailed in our breakdown on where accounting transactions are first recorded, raw source data collected at step one serves as the sole input for journalizing entries. If an unverified transaction slips through this initial gate, it corrupts the downstream records before anyone opens the general ledger.
Common Source Documents Used in Transaction Identification
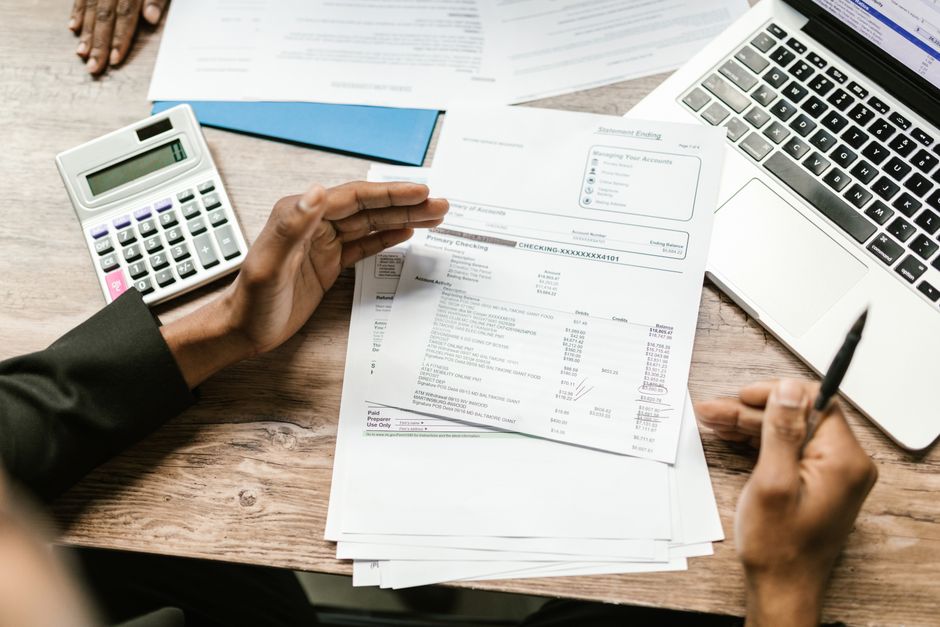
Accountants do not create journal entries based on verbal promises or informal messages. Every transaction must be backed by a physical or digital source document that acts as hard evidence for internal risk controls and external auditors.
The table below highlights the primary source documents used during the transaction identification stage, alongside the financial accounts they impact:
| Source Document | Operational Trigger | Primary Accounts Affected |
|---|---|---|
| Vendor Sales Invoice | Receipt of inventory or commercial services on credit | Accounts Payable, Expense / Inventory |
| Customer Sales Receipt | Point-of-sale cash payment received for merchandise | Cash, Revenue |
| Bank Deposit Slip | Funds transferred into corporate checking account | Cash, Accounts Receivable |
| Employee Electronic Timesheet | Work performed during a bi-weekly payroll window | Payroll Expense, Accrued Wages Payable |
| Equipment Purchase Contract | Acquisition of heavy machinery under legal agreement | Fixed Assets (PP&E), Long-Term Debt |
Evaluating these records requires strict adherence to timing standards. Under accrual accounting guidance maintained by the Financial Accounting Standards Board (FASB), revenue and expenses are recognized when earned or incurred, regardless of when cash physically moves. To explore how timing alters transaction identification, review our analysis comparing cash vs accrual accounting methods.
Real-World Examples of Identifying vs. Filtering Transactions
Distinguishing recordable transactions from non-transactional business events is one of the most critical responsibilities during step one. Misinterpreting an operational milestone as a financial exchange creates artificial inflation or deflation across company accounts.
Consider three common corporate scenarios:
Example 1: Recordable Credit Purchase
A manufacturing firm receives 500 units of raw steel valued at $45,000 alongside a vendor invoice specifying payment terms of Net 30. Because the physical goods have arrived and a legal liability was incurred, this is a recordable transaction. The accountant identifies an increase in inventory ($45,000 asset) balanced by an increase in accounts payable ($45,000 liability).
Example 2: Non-Recordable Contract Execution
A company signs a non-binding memorandum of understanding (MOU) to hire a new Vice President of Sales at an annual salary of $250,000 USD, scheduled to start next month. A non-binding MOU for a $250k executive salary feels like major business progress, but to an accountant, it carries the exact financial weight of a lunch order until services are rendered. No cash changed hands, no work was completed, and no liability exists on the contract execution date. This event is filtered out and omitted from journal logs.
Example 3: Recordable Prepaid Service Expense
An enterprise pays $12,000 upfront for a 12-month commercial property insurance policy. The accountant identifies a financial transaction: cash decreases by $12,000, while a prepaid insurance asset increases by $12,000. Under accrual rules, the expense itself is recognized incrementally over the next 12 months, rather than taken all at once.
A controller described spending three months reconstructing journal entries after a mid-year ERP switch with no data migration plan—every reconciliation had to be done manually against PDFs because initial transaction source documents were misfiled.
Reddit r/accounting
How Many Steps Are in the Full Accounting Cycle?
While software user interfaces present accounting workflows in various ways, standard corporate reporting consists of eight core steps recognized by standard-setting bodies like the American Institute of Certified Public Accountants (AICPA). These steps form a closed-loop framework that runs continuously over monthly, quarterly, or annual fiscal periods.
- Identify and Analyze Transactions: Gathering source documents (invoices, receipts, contracts) and verifying their monetary impact on corporate accounts.
- Record Transactions in a Journal: Log entries chronologically using double-entry bookkeeping (matching debit and credit values).
- Post Entries to the General Ledger: Transfer journalized totals into individual T-accounts organized by asset, liability, equity, revenue, and expense categories.
- Prepare an Unadjusted Trial Balance: Calculate ending account balances at the close of the period to confirm total debits equal total credits.
- Formulate Adjusting Entries: Record accruals, deferrals, depreciation, and inventory adjustments to comply with revenue recognition and matching principles.
- Prepare an Adjusted Trial Balance: Re-run the balance test after adjusting entries are processed to verify mathematical accuracy before financial reporting.
- Generate Financial Statements: Compile the adjusted ledger balances to build the Income Statement, Balance Sheet, Statement of Cash Flows, and Retained Earnings Statement.
- Close the Books: Zero out temporary revenue and expense accounts by shifting net income into permanent retained earnings, resetting the ledger for the subsequent period.
Executing this sequence consistently reinforces internal transparency. For a deeper look into how accurate recordkeeping fuels business decision-making, see our guide on the importance of accounting in business operations.
Automation and AI at Step One: Moving from Manual Logs to Optical Ingestion
The manual collection of paper receipts and hand-typed invoice entry at step one is rapidly giving way to automated cloud infrastructure. Market analysis published by Grand View Research revealed that the global accounting software market reached $19.4 billion USD in 2024 and is projected to expand to $31.3 billion USD by 2030, driven largely by enterprise investment in automated transaction ingestion.
Modern platforms utilize Optical Character Recognition (OCR) and machine learning models to automatically scan vendor PDFs, parse line items, and extract key fields such as invoice numbers, tax subtotals, and vendor IDs. Research from the McKinsey Global Institute estimated that up to 50% of routine accounting tasks can be automated using established technologies.
However, automation does not eliminate human responsibility at step one. Software algorithms frequently misinterpret complex contract structures, duplicate payments, or misclassify capitalized asset software development costs under updated standards like FASB ASU 2025-06.
Automation that skips the review step is not automation — it’s risk transfer. The liability doesn’t disappear because a machine ingested the invoice; someone still has to verify that the underlying economic exchange occurred. (Vendor sales demos love showing instant invoice OCR scanning, right up until a scanned receipt features coffee stains over the sales tax subtotal.)
Frequently Asked Questions
The software will continue to capture data faster. The responsibility to verify what actually happened remains yours. Excel won’t complain if you feed it fiction, but the auditors will.
About the Author