Photo by: josemiguel67bio jose miguel via Pexels
TL;DR: The father of accounting is Fra Luca Bartolomeo de Pacioli (c. 1447–1517), an Italian Franciscan friar, university mathematician, and Renaissance polymath who published the first printed treatise on double-entry bookkeeping in Venice in 1494. Contained within his seminal compendium Summa de arithmetica, geometria, proportioni et proportionalita, his 27-chapter accounting manual established the debits, credits, journals, and ledgers that still underpin international commerce and cloud financial systems.
Luca Pacioli did not invent the concept of trade, nor did he construct the first ledger entry in human history. Commercial merchants had tracked goods across Mediterranean trading routes for generations before his birth. Yet the definitive answer to who is the father of accounting remains Fra Luca Bartolomeo de Pacioli, who systematized double-entry bookkeeping so thoroughly in 1494 that global business adopted his structural logic across five centuries. Before his Venetian treatise was printed on movable type, merchant records were a fragmented patchwork of informal notes. After his manual circulated across Renaissance Europe, accounting transformed into a rigorous mathematical discipline with synchronized balance checks.
Table of contents
- Who was Luca Pacioli, and why is he called the father of accounting?
- Key historical numbers behind Luca Pacioli and early accounting
- Did Luca Pacioli invent double-entry bookkeeping or document it?
- Memorandum, Journal, and Ledger: How Pacioli structured the three-book system
- Pacioli vs. Benedetto Cotrugli: How historical accounting systems compared
- The mathematical partnership: Luca Pacioli and Leonardo da Vinci
- The operational reality: What early Venetian accounting teaches modern finance teams
- Frequently asked questions
- Conclusion and enduring legacy in modern accounting systems
Who was Luca Pacioli, and why is he called the father of accounting?
Fra Luca Bartolomeo de Pacioli was an Italian Franciscan friar and itinerant mathematics professor who earned the title “Father of Accounting” by publishing the first comprehensive, printed explanation of double-entry bookkeeping, according to historical archives preserved by the Institute of Chartered Accountants in England and Wales (ICAEW).
Born around 1447 in Sansepolcro, Tuscany, Pacioli received an applied commercial education rather than traditional monastic schooling. He studied mathematics under the pioneering painter and geometrician Piero della Francesca before moving to Venice as a tutor to the sons of prominent merchant Antonio de Rompiasi. Immersed in the Venetian trading houses, Pacioli observed how sea merchants tracked multifaceted shipping ventures, diverse currencies, and credit relationships without losing operational oversight.
Pacioli joined the Order of Friars Minor (Franciscans) in the early 1470s, subsequently teaching mathematics at the universities of Perugia, Rome, Naples, and Pisa. His academic prestige culminated in the publication of his masterwork, Summa de arithmetica, geometria, proportioni et proportionalita, printed in Venice on November 10, 1494, by paganino de paganini. While the textbook served as an exhaustive survey of Renaissance mathematics, its most influential section was Section IX, Title 11: Particularis de Computis et Scripturis (Particulars of Reckonings and Writings). This 27-page practical manual laid down the formal architecture of double-entry accounting.
Commercial records prior to Pacioli’s treatise suffered from subjective notations and single-entry ambiguity. Merchants recorded cash inflows and outflows, but single-entry records failed to capture asset depreciation, uncollected receivables, or equity claims simultaneously. Codifying the Venetian double-entry method elevated bookkeeping into an integrated verification system where every economic transaction required an offsetting debit and credit, establishing the foundational concepts explored in the seven pillars of accounting.
Key historical numbers behind Luca Pacioli and early accounting
- Publication year of the Summa: 1494, printed in Venice using Gutenberg-style movable type (ICAEW Historical Archives, November 1494).
- Treatise section length: 27 distinct operational chapters dedicated specifically to merchant bookkeeping and trial balance procedures (ICAEW Historical Collection).
- Earliest surviving municipal double-entry ledgers: 1340, recorded by the Massari (treasurers) of the Commune of Genoa (Cambridge University Press Archival Records).
- Earliest unpublished double-entry manuscript: 1458, drafted by Ragusa merchant Benedetto Cotrugli (published posthumously in 1573).
- First printed rule of 72 formula: 1494, documented in Pacioli’s Summa to calculate investment doubling periods at annual interest rates.
Did Luca Pacioli invent double-entry bookkeeping or document it?
Historical evidence confirms that Luca Pacioli did not invent double-entry bookkeeping. Italian merchant communities in Genoa, Florence, and Venice had utilized early variations of reciprocal ledger recording for more than 150 years prior to the publication of the Summa. Extant fragments from the 1211 ledgers of Florentine bankers display early two-sided accounts, and municipal records from Genoa in 1340 prove that local financial administrators maintained formal double-entry accounts with separate debit and credit columns.
Pacioli made no claim of invention in his writing. He explicitly referred to the system as alla Veneziana (“according to the Method of Venice”), openly crediting the commercial practices of Venetian traders. What made Pacioli the recognized father of the discipline was his synthesis, clarity, and publication distribution:
- Vernacular instruction over academic Latin: Pacioli wrote in the Venetian-Tuscan mercantile dialect rather than Latin, making the textbook immediately accessible to working bookkeepers, apprentices, and active business proprietors.
- The power of the printing press: Earlier accounting treatises existed only as hand-copied manuscripts confined to private merchant dynasties. Movable-type printing allowed hundreds of copies of the Summa to spread across trade routes into France, Germany, the Netherlands, and England.
- Codification of a complete operational cycle: Rather than discussing bookkeeping in abstract terms, Pacioli presented an end-to-end procedural workflow spanning daily diary entries, journal validation, general ledger posting, and year-end inventory closing.
Memorandum, Journal, and Ledger: How Pacioli structured the three-book system
Pacioli organized financial recordkeeping into three sequentially linked books: the Memorandum (Memoriale), the Journal (Giornale), and the Ledger (Quaderno). This linear sequence established how financial transactions were captured, converted, and classified across commercial operations.
- The Memorandum (Memoriale): The frontline intake log where sales clerks and traders noted daily business events as they occurred. Transactions were entered chronologically in whatever currency or commodity unit was exchanged, preserving the detailed terms of sale, weight, quantity, and payment promises before formalized accounting occurred. Modern accountants exploring where accounting transactions are first recorded recognize the Memorandum as the ancestor of modern source document filing.
- The Journal (Giornale): The intermediate validation record. In this book, transactions were translated into standardized local currency (the Venetian Ducat) and formatted into debits and credits using the Latin terms Per (debtor) and A (creditor). The Journal established transaction chronology and explained the underlying economic reason for each entry.
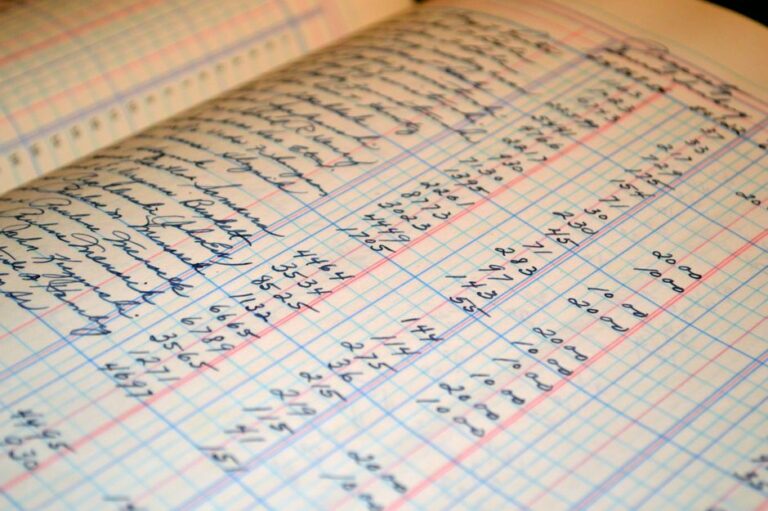
- The Ledger (Quaderno): The master financial summary, indexed alphabetically and organized by double-entry accounts. Debits sat on the left-hand page, credits on the right-hand page. Each transaction recorded in the Journal was posted to two distinct ledger accounts, ensuring that total debits equaled total credits.
Pacioli also introduced the operational protocol of the trial balance (Bilancio del Libro). Before opening a new ledger book, bookkeepers compiled all debit balances and credit balances onto a single summary sheet. If the two totals diverged, bookkeepers audited individual journal entries until the error was located. The step-by-step logic Pacioli designed laid the groundwork for the modern sequence of accounting cycle steps.
Pacioli vs. Benedetto Cotrugli: How historical accounting systems compared
Accounting historians frequently contrast Luca Pacioli with Benedetto Cotrugli (Beno Kotruljević), a merchant from Dubrovnik who wrote Della mercatura et del mercante perfetto in 1458—thirty-six years before the Summa. Evaluating the structural attributes of both systems clarifies why Pacioli became the foundational authority for international financial education.
| Dimension | Benedetto Cotrugli (1458 / 1573) | Luca Pacioli (1494) | Modern Cloud AIS / ERP |
|---|---|---|---|
| Year Written & Distributed | Written 1458; unpublished manuscript until 1573. | Written and printed simultaneously in 1494 via Venetian movable type. | Continuous cloud delivery via SaaS architectures. |
| Bookkeeping System | Outlined 3-book concept (Memoriale, Giornale, Quaderno). | Comprehensive operational manual detailing rules, debits/credits, and posting logic. | Automated subledgers feeding real-time general ledger via APIs. |
| Target Audience | Private aristocratic merchant circles in Dubrovnik and Naples. | University scholars, working merchants, apprentices, and commercial traders. | Enterprise controllers, financial analysts, operations teams, and external auditors. |
| Primary Language | Italian manuscript copied by scribes. | Venetian mercantile vernacular printed in high volume. | Relational SQL databases and digital API microservices. |
| Trial Balance Procedure | Brief conceptual mention of year-end account alignment. | Rigorous step-by-step instructions for trial balance matching and error reconciliation. | Automated instant trial balances and algorithmic anomaly detection. |
Modern cloud architectures expand upon the framework Pacioli established. As detailed in our breakdown of accounting information systems, contemporary ERP suites replace hand-bound ledgers with relational database tables, yet the core requirement that every debit entry must balance an offsetting credit remains unchanged.
The mathematical partnership: Luca Pacioli and Leonardo da Vinci
Beyond his accounting contributions, Pacioli was a central figure in High Renaissance intellectual circles. In 1496, Ludovico Sforza, Duke of Milan, invited Pacioli to his court to teach mathematics. In Milan, Pacioli met and lived with Leonardo da Vinci, establishing an extraordinary intellectual collaboration.
Leonardo sought out Pacioli to master proportional geometry, perspective, and Euclidean mathematics. In return, Leonardo provided sixty detailed geometric illustrations for Pacioli’s subsequent treatise, De divina proportione (On the Divine Proportion), printed in Venice in 1509. Leonardo credited Pacioli in his personal notebooks with teaching him the geometric proportions that informed masterpieces such as The Last Supper and the Vitruvian Man.
Pacioli viewed accounting not as a narrow administrative chore, but as an expression of divine cosmic harmony. For Pacioli, a balanced balance sheet reflected the same mathematical symmetry and equilibrium that governed geometry and the physical universe. This philosophical view elevated accounting from a bookkeeping trade to an intellectual pursuit requiring rigorous integrity.
The operational reality: What early Venetian accounting teaches modern finance teams
Centuries after Pacioli’s death, discussions among working CPAs frequently return to whether bookkeeping systems represent created conventions or discovered mathematical truths.
Practicing accountants debating the philosophical roots of the profession noted that while double-entry bookkeeping was formalized in Renaissance Italy, the underlying mathematical duality represents an inescapable truth of commercial exchange: every asset transferred must originate from a distinct liability claim or equity ownership, meaning Pacioli uncovered a natural law of trade rather than inventing an arbitrary corporate ritual.
Reddit r/Accounting
Venetian merchants recognized early what modern controllers frequently forget during quarterly closes: recording financial events promptly is non-negotiable. Pacioli warned that failing to maintain updated daily records invites theft and business failure, famously advising that a merchant must never go to sleep until debits equal credits. In an era where companies debate real-time closing schedules versus month-end batch processing, the discipline Pacioli mandated remains the foundation of organizational control.
Applying rigorous recognition standards separates reliable financial disclosures from guesswork. When entities evaluate transactional timing under cash vs accrual accounting models, they execute the identical matching logic that Pacioli codified over five hundred years ago.
Frequently asked questions
Conclusion and enduring legacy in modern accounting systems
Fra Luca Pacioli transformed accounting from an informal craft into a disciplined commercial science. By publishing the Venetian double-entry method on movable type, he established an immutable system of checks and balances that empowered the expansion of international commerce, corporate joint ventures, and global capital markets. While modern finance now operates across distributed cloud servers and automated ledgers, every journal entry, trial balance reconciliation, and corporate balance sheet traces its lineage directly back to the 27-chapter manual Pacioli printed in Venice in 1494.
About the Author